Quick answer
US vs Canada medical debt is a different risk, not a magic wipe. Once you are enrolled in a provincial plan, medically necessary hospital and physician services cannot be billed to you under the Canada Health Act. That does not erase US bills you already owe, and it does not make drugs, dental, or vision free.
On the US side, the KFF 2025 Employer Health Benefits Survey found average family premiums of $26,993, with workers paying $6,850 toward that premium. The average deductible among covered workers in a plan with a general annual deductible was $1,886 for single coverage. Published household surveys in 2024 also found medical debt common even among insured US families.
Calculate it: do health savings beat the tax gap?
US premiums and deductibles are only half the story — Canadian income tax is usually higher. Plug in your salary, state, and what you pay for health insurance now to see which side comes out ahead.
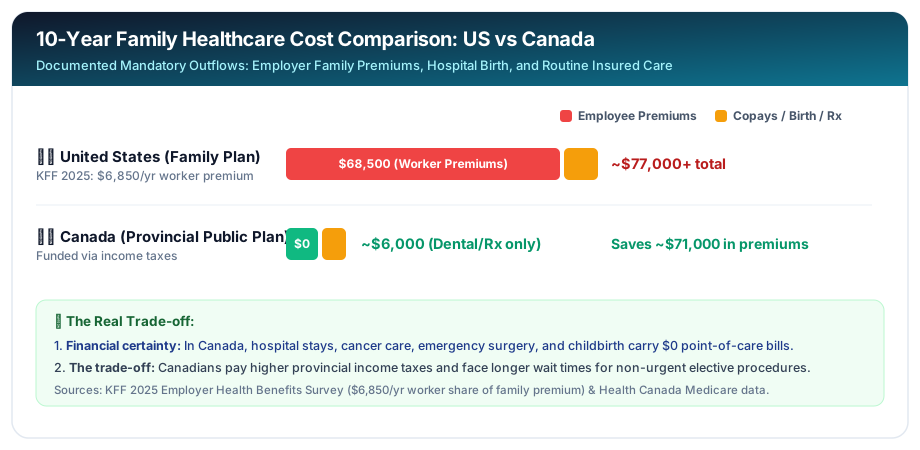
The 10-year family math (illustration)
The table uses the KFF 2025 average worker family contribution on the US premium line. Other US rows are a conservative household illustration, not a quote for your plan. The Canada column assumes you are enrolled in a provincial plan for insured hospital and doctor services, plus typical employer dental/vision benefits.
| Expense Category (10 Years) | 🇺🇸 United States | 🇨🇦 Canada |
|---|---|---|
| Employee Premiums (Payroll deductions) |
$68,500 KFF 2025: $6,850/yr worker share |
$0 No public-plan premium for insured services |
| Deductibles & Co-pays (Illustration; KFF 2025 single deductible avg $1,886) |
Varies by plan Family deductibles are often higher |
$0 For insured hospital/doctor visits |
| Having a Baby (Standard delivery) |
$3,000 - $5,000 | $0 |
| Dental & Vision & Rx (After employer benefits) |
$5,000 | $6,000 (Not universally covered) |
| Documented premium gap (10 years) | $68,500 worker premiums | $0 public-plan premiums |
Using only the KFF worker premium, a US family at the 2025 average contributes about $68,500 over 10 years before deductibles, copays, or a serious diagnosis. Canada funds insured hospital and doctor care through taxes instead of that premium. Higher Canadian income tax is the trade-off — compare both on the tax guide.
How Canadian healthcare works for newcomers
When does coverage start?
It depends on the province, and the old “three months everywhere” rule is outdated. Ontario has no OHIP waiting period if you are eligible. B.C. MSP still waits the rest of your arrival month plus two months. Quebec RAMQ usually waits up to three months. Alberta can start on your residency date if you apply within three months from outside Canada. Keep private coverage until the provincial plan confirms the start date.
What IS covered?
Anything medically necessary. Doctor visits, emergency room trips, surgeries, blood tests, X-rays, MRI scans, and hospital stays. You walk into the clinic, show your provincial health card, and you walk out. There is no billing department.
What ISN'T covered?
Canada's system does not cover prescription drugs (though prices are strictly regulated, so cash prices are lower than the US), dental care, or vision care. To cover these, most full-time jobs provide "Extended Health Benefits." These plans generally cover 80% to 100% of dental and prescription costs, with employer-funded plans often requiring no employee-paid monthly premiums.
The Trade-Off: Wait Times
The main complaint about Canadian healthcare is wait times. If you need a hip replacement or a non-urgent MRI, you will wait longer in Canada than you would in the US (if you had premium US insurance). The system prioritizes based on medical urgency, not ability to pay. If you have a heart attack or cancer, you are treated immediately by world-class specialists.
Frequently asked questions
See How Healthcare Savings Impact Your Budget
Our cost of living calculator incorporates estimated healthcare costs and tax rate adjustments for each province.